Check Your CIBIL Score for an Education Loan
When applying for an education loan, your CIBIL score is an important factor in the application assessment process. It reflects your credit history and financial behaviour, helping us better understand your credit profile. A strong CIBIL score can improve your overall eligibility and may support a smoother loan application journey.
Knowing your CIBIL score before applying helps you understand your current credit standing and identify areas that may need improvement. If you're applying with a co-applicant, their credit profile may also play a role in the assessment process.
With Poonawalla Fincorp, you can quickly and easily check your CIBIL score online. Take the first step towards achieving your higher education goals by understanding your credit profile and applying with confidence.
Why is a CIBIL Score Important to Get an Education Loan?
A good CIBIL score can provide you with several advantages for an Education Loan, such as:
- Improved chances of Education Loan approval
- Better confidence during evaluation
- Easier loan processing
- Higher loan eligibility, depending on internal policies
- Possibility of competitive loan terms
Since many students may not have an established credit history, the co-applicant's financial profile, including their credit score and repayment behaviour, is often considered during the evaluation process.
Minimum CIBIL Score for Education Loan
The minimum CIBIL score required to secure an Education Loan is 750 or above. A score of 750 or higher shows you are a reliable borrower and increases your chances of loan approval. If you have a low CIBIL score, a co-applicant with a strong credit history or collateral can significantly improve your chances of approval.
A good CIBIL score can strengthen an Education Loan application, but it isn't the only factor. Academic performance, the chosen course, the co-applicant's financial profile, and repayment capacity may also play an important role in determining eligibility.
| CIBIL Score Range | Approval Possibility | Typical Outcome |
| 750 and above | Very High | Faster processing and favourable loan terms |
| 700 - 749 | High | Good approval chances if income and documents are strong |
| 650 - 699 | Moderate | Additional verification may be required |
| 600 - 649 | Limited | Co-applicant strength becomes important |
| Below 600 | Challenging | Approval depends heavily on co-applicant profile and repayment capacity |
The above information is indicative and actual eligibility may vary depending on applicable assessment criteria.
Here are the general eligibility requirements:
- Nationality: The applicant must be an Indian citizen.
- Age: Should generally be 18 years or above at the time of application.
- Admission Status: Must have secured admission to a recognised institution in India or abroad.
- Co-applicant Requirement: A co-applicant (parent, guardian, or spouse) is usually required for the loan.
- Co-applicant’s Financial Background: The co-applicant should have a stable income source and a good credit history.
- Academic Performance: Academic performance and past records are taken into account.
Before applying for an education loan, check the eligibility criteria and ensure you meet the applicable requirements.
A low CIBIL score does not always prevent you from pursuing higher education. Education loan applications are typically assessed using multiple eligibility parameters rather than credit score alone.
If You Are a First-Time Borrower
Many students may not have an established credit history at the time of applying for an Education Loan. In such cases, greater importance may be given to the co-applicant's financial profile and supporting documents.
If Your CIBIL Score Is Low
Approval possibilities may still depend on factors such as:
- Academic performance
- Admission to a recognised institution
- Chosen course and future career prospects
- Co-applicant's income and financial stability
- Existing repayment obligations
If You Have a Strong Co-applicant
A financially stable co-applicant with a healthy credit profile can strengthen the application by demonstrating additional repayment support.
For most education loan applications, a parent, spouse, sibling, or guardian acts as a co-applicant. Their credit profile may influence the overall assessment of the application.
Impact of a Strong Co-applicant Credit Score
A strong co-applicant profile may:
- Improve overall application strength
- Demonstrate repayment capability
- Support higher loan eligibility, subject to assessment
- Strengthen the financial profile submitted with the application
- Impact of a Low Co-applicant Credit Score
Impact of a Low Co-applicant Credit Score
A lower co-applicant score may:
- Trigger additional verification requirements
- Affect loan eligibility assessment
- Lead to a closer review of debt-to-income obligations
Here are a few things you must keep in mind before applying for an Education Loan:
- Estimate Your Funding Requirement: Determine how much you need to cover any educational costs; this will give you a clear understanding of your financial needs. Plus, you can avoid borrowing more than necessary and minimise your financial burden in the long run.
- Minimum and Maximum Funding Available: Education loan eligibility and sanctioned amounts are determined based on multiple assessment criteria, including the course fee, institute tier, and overall funding limits set by lending policies. Before applying, evaluate your total funding requirements to ensure the eligible loan amount aligns comprehensively with your expenses.
- Rate of Interest: It's crucial to compare the interest rates and choose a loan with the most competitive rate. Remember, a lower monthly interest rate translates to lower EMIs and a reduced overall interest over the loan period.
- Requirement of Collateral: Collateral requirements for education loans may vary depending on factors such as the loan amount and eligibility criteria. Before proceeding, review whether any security is required and understand the terms, repayment obligations, and potential implications of loan default on pledged assets.
- Pre-payment or Foreclosure Charges: In case you want to foreclose your loan, it's essential to understand the loan terms and conditions related to pre-payment and foreclosure charges and factor them into your repayment strategy.
- Repayment Tenure: Before applying for an Education Loan, evaluate the available repayment tenure options and choose a repayment schedule that suits your financial circumstances, expected income, and long-term repayment goals.
You can check your CIBIL score in 3 easy steps:
Step 1: Visit Poonawalla Fincorp’s official website.
Step 2: Click on the ‘Free CIBIL Check’ button.
Step 3: Fill in the required details and submit.
Your CIBIL score will be visible on your screen. Your CIBIL report will also be sent to your registered mobile number and email ID.
Applicants with a low credit score can still improve their chances of approval for an Education Loan by following a few important steps.
- Apply with a Strong Co-applicant: A co-applicant with a stable income and a healthy credit score may strengthen the loan application.
- Repay Existing Dues on Time: Timely repayment of loans and credit card bills may gradually improve the credit profile.
- Avoid Missing EMI Payments: Missed payments may negatively affect the CIBIL score and repayment history.
- Reduce Existing Debt: Lower outstanding debt obligations may improve overall financial stability.
- Correct Errors in the Credit Report: Review your credit report regularly and report any incorrect information if identified.
Careful financial planning and maintaining a healthy repayment record may improve the chances of education loan approval over time.
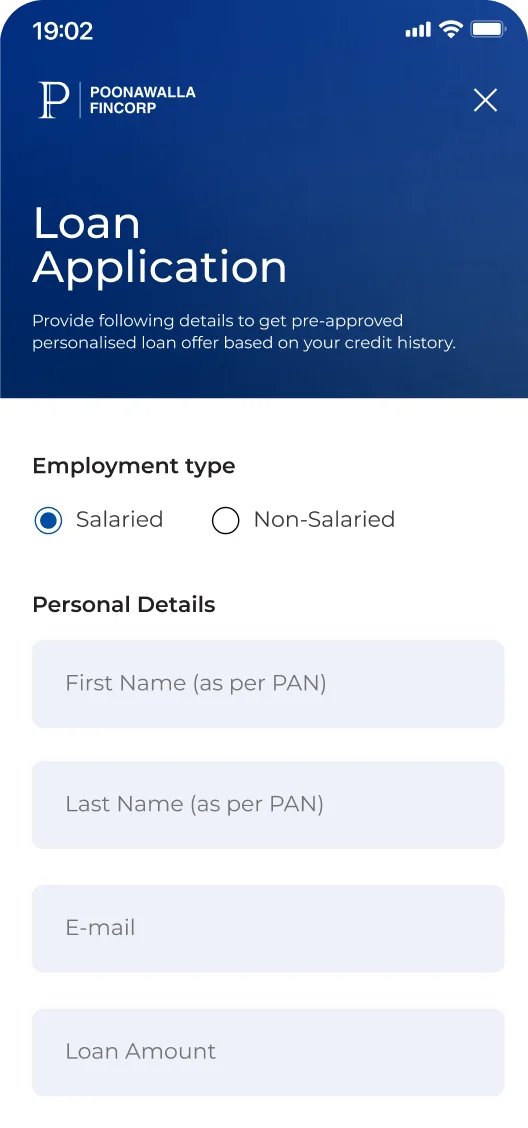
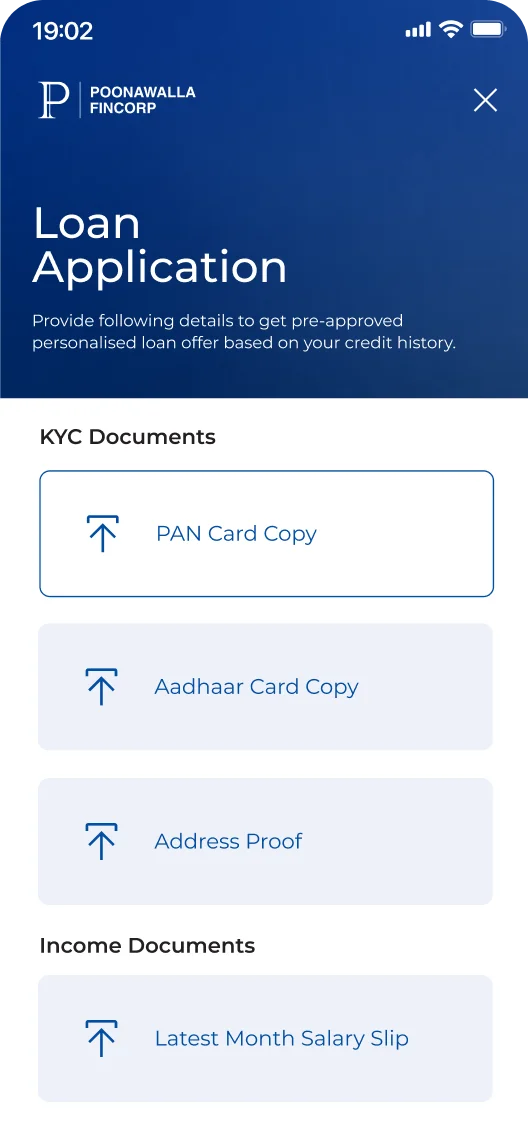

Happy Customers, Happy Us
Throughout my loan journey, the Poonawalla Fincorp team showcased exceptional dedication, in-depth product knowledge, and a truly customer-centric approach. At every stage, they guided me with patience and clarity, making the entire process seamless, transparent, and timely. Their proactive communication and unwavering willingness to go the extra mile are a testament to the organization’s high standards of service excellence. Such professionalism not only fosters strong customer trust but also reinforces Poonawalla Fincorp’s reputation as a leading, customer-focused financial institution. I extend my heartfelt thanks to the entire team for their commendable efforts and wish them continued success in all their endeavors.

I am incredibly grateful for the outstanding support I received throughout my loan process. The guidance provided made every step feel manageable and stress-free. What stood out most was the humility and genuine willingness to help at every stage, qualities that made a significant difference in my experience. Without this support, the journey would have been far more challenging. I truly appreciate the dedication and helpful nature that was consistently demonstrated. The efforts put forth were invaluable, and I feel fortunate to have worked with someone so committed and supportive.
It was really great working with Poonawalla Fincorp. Thanks to the support and coordination by the team. I was able to get a significant portion of my requirements despite having a bit of a mess in my financial records. The loan processing and disbursement process at Poonawalla Fincorp was super smooth. They were incredibly cooperative and helpful. I’m looking forward to building a healthy relationship with them in the future. Thank you.
Poonawalla Fincorp’s Pre-owned Car Loan made the entire financing process effortless. The loan approval was quick, and the minimal documentation made it even more convenient. Within just a couple of days, the funds were disbursed, allowing me to purchase a well-maintained pre-owned vehicle without any hassle. The repayment options were flexible, and the entire experience was seamless. Thanks to Poonawalla Fincorp, I could get my car without any financial strain. Highly recommended!
Securing a loan to purchase a commercial property with rental income was crucial for my business. Having previously worked with Poonawalla Fincorp, I was confident in their services. The process was incredibly smooth and transparent. The quick disbursement and excellent post-sales support made the entire experience stress-free. Thanks to Poonawalla Fincorp, I now own a prime commercial property in Mumbai, which has significantly boosted my business. Their quick turnaround time and excellent post-sales support made all the difference. I wholeheartedly recommend them to anyone in need.
I had a great experience with Poonawalla Fincorp’s Pre-owned Car Loan. The offered loan amount was as per my expectations, and the entire process was smooth and hassle-free. The documentation was minimal, and the loan was disbursed in just two days! What stood out was the flexibility—repayment was easy, and the EMI structure was well-planned. The loan approval process was straightforward, making it convenient to get the car I wanted without any delays. Overall, the service was excellent, and I highly recommend Poonawalla Fincorp to anyone looking for an easy and quick loan process!
A friend in need, is a friend indeed. Poonawalla fincorp has been like one of those friends for me, who has supported me in my journey. With no hidden charges and no prepayment charges, the company has provided me with the adequate funds I needed for me professional practice. From the loan application process to the disbursal of funds, I did not face any problems. My experience was hassle-free and smooth. Not just me, all my fellow professionals and friends have had a wonderful experience with Poonawalla Fincorp’s Professional Loan.
I am practicing Chartered Accountant (CA) based out of Hubli. There were working capital issues that i was facing like upgrading my firm’s overall infrastructure, hiring well-qualified staff and digitization. Poonawalla fincorp hab been of great support when it comes to funding these requirements. I’ve got one of the best interest rates available in the market, my documentation process was fast & hassle-free. and the digital application process made it very simple to get a Professional Loan as a CA. I recommend to CAs to consider Poonawalla Fincorp for their working capital or any other funding requirements.
I run a chain of farmacy stores with 5 branches in pune. With the growing polpularity of home delivery, my customers were expecting the same from me as well. However, the extra capital requirement made it difficulf for me to hire delivery persons. With Poonawalla fincorp’s Business loan, I am now able to compete with online pharmacy retailers, manage working capital and upgrade my system. My customers have grown 50-60%. The loan applicatipn process is digital, simple and speedy. I was delighted to get my loan amount disbursed quickly, allowing me to upgrade my operationg seamlessly.
Get exclusive access to simplified
Personal Finance Information at
Poonawalla Fincorp’s
FinHub
Frequently Asked Questions
Generally, the minimum CIBIL score required for an Education Loan is around 750. However, it also depends on both the internal policies and the applicant’s financial situation.
A CIBIL score for students is a numerical representation of credit health based on credit usage and repayment behaviour. Along with factors such as academic profile, course details, and co-applicant information, it may influence Education Loan eligibility.
Yes, many students applying for an education loan may not have a credit history. In these situations, the overall application may be assessed based on factors such as the co-applicant's financial profile, academic performance, chosen course, and repayment capacity.
Check your CIBIL score annually for regular monitoring to ensure your financial stability. Make sure you review it a few months before applying for your Education Loan to ensure accuracy.
No, there are no legitimate quick fixes for improving your credit score. Building a good credit history requires time, consistency, and responsible financial management practices.
Maintaining a good credit mix and credit card usage of 30% helps maintain a good CIBIL score. Other than this, paying all bills and EMIs on time, having a healthy mix of credit accounts and avoiding closing old credit accounts helps maintain a good credit score.
Yes, the credit profile of the co-applicant is often an important factor in an Education Loan application. Since many students may not have an established credit history, the co-applicant's CIBIL score, repayment behaviour, income stability, and overall financial profile can contribute to the overall strength of the application. Avoiding specific score thresholds keeps the content accurate and compliant, as eligibility criteria may change over time.
A CIBIL score of 750 or above is generally considered strong. However, education loan eligibility depends on several factors, including academic background, co-applicant profile, income, and overall repayment capacity.
Yes, eligibility may still be possible with a 650 CIBIL score. The final assessment typically considers multiple factors beyond the credit score alone.
Not always. Many students are first-time borrowers and may not have an established credit history. In such cases, the co-applicant's financial profile may play a significant role.
Since parents often act as co-applicants, their credit history and repayment behaviour may influence the overall assessment.
Timely EMI repayment can help build a positive credit history and maintain a healthy CIBIL score over time.
Applicants with limited or no credit history may still be considered based on factors such as academic credentials, institution, course details, and co-applicant profile.
Submitting multiple loan applications within a short period may lead to multiple credit enquiries, which could have an impact on your credit profile.