
Get a Working Capital Loan for Daily Business Expenses
A working capital loan gives businesses direct access to funds to manage everyday operational expenses and short-term cash flow needs. From purchasing raw materials and maintaining inventory to settling supplier invoices, salaries, rent, and utility bills, working capital finance ensures operational continuity without straining cash reserves.
With a working capital loan from Poonawalla Fincorp, eligible businesses can secure funding up to ₹1 Crore. Benefit from competitive interest rates starting at 15%* p.a. and flexible repayment tenures extending up to 60 months. Choose funding aligned with your business cycle to manage seasonal demand, replenish stock, or bridge cash flow gaps. Apply now!
Working Capital Loan EMI Calculator
Knowing your monthly commitment upfront helps you plan better. Use the working capital loan EMI calculator to estimate your monthly outgo in seconds based on your target loan amount, tenure, and applicable interest rate.
Optimise Your Business Loan Experience
With Monthly Budget Planning
Why Choose Our Working Capital Loan?
 Collateral-free
Loan
 Minimal
Documentation
 No Hidden
Charges
 Minimal
Documentation
 Simple Eligibility
Criteria
 Competitive
Interest Rate
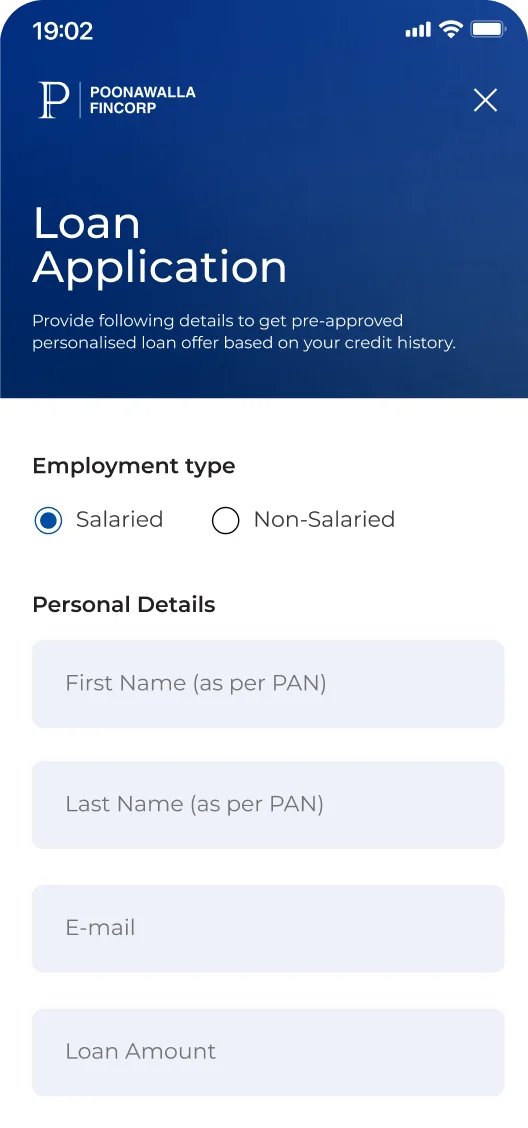
Apply for a Business Loan Online in Just 3 Steps

Click on "Apply Now”
Tap the "Apply Now" button to initiate your application.

Enter Details
Enter your DOB, PAN card number, monthly income, and residential details.

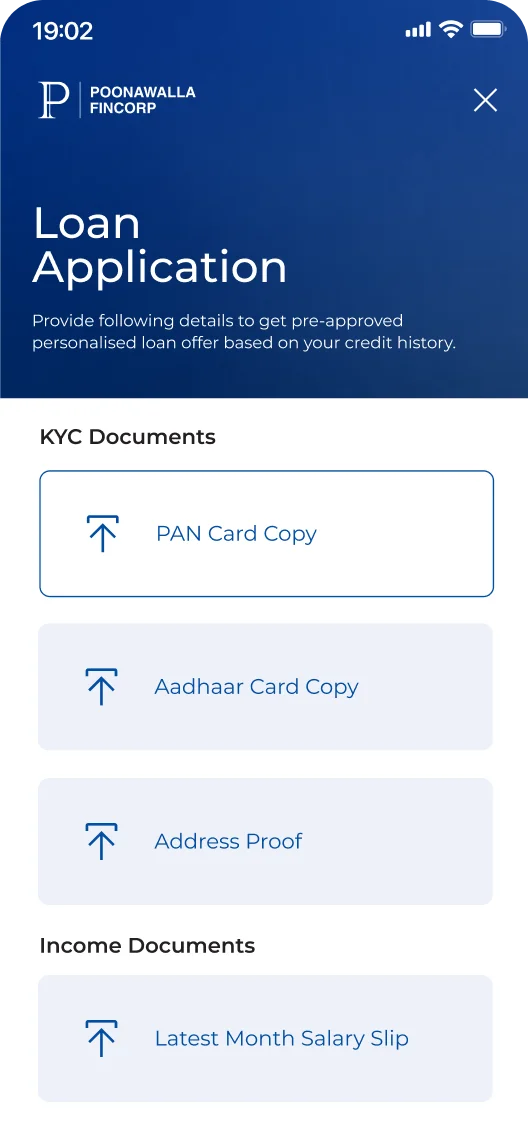
Upload Documents
Upload the necessary documents for quicker approval.
On successful verification, the loan amount will be disbursed into your bank account instantly.
Fulfil our simple eligibility criteria to avail of the loan:
|
Factor |
Working Capital Loan Requirements |
|
Nationality |
Indian Citizen |
|
Age |
Between 24 and 65 years |
|
Business Vintage |
Minimum 2 years of continuous business operations |
|
Annual Turnover |
At least ₹6 Lakh |
We offer working capital loans with minimal documentation, helping eligible businesses access funds for their operational requirements through a convenient application process.
KYC Documents
-
Personal Documents (Proprietor / Partner / Director): PAN Card, Aadhaar Card, Driving License, Voter ID, or Passport. Proof of residence is required if current address differs from the official identity document.
-
Business Address Proof: Registration proof and address documentation (if different from registered business address).
Business Documents
- GST Registration Certificate, Udyam Registration Certificate, and other statutory registration certificates.
Financial Documents
Bank account statement for the last 6 months.
Check out the required business loan application documentation in detail.
Poonawalla Fincorp offers working capital loans at highly competitive interest rates, ensuring that you get the best possible value. All applicable charges are communicated clearly with no hidden fees.
Default Charges: Penalty will be charged for nonpayment of EMI amount and for non-compliance of material terms and conditions, as more particularly specified at Default Charges.pdf
*T&C Apply
Businesses can access various forms of working capital finance tailored to their specific needs. The primary types of working capital loans include:
- Overdraft Facility: Sanctioned credit line allowing withdrawals up to a specified limit beyond your account balance. Interest is calculated strictly on the utilised amount, providing optimal cash-gap flexibility.
- Cash Credit: Revolving credit facility secured against current assets like stock and accounts receivable, ideal for daily operational cash commitments.
- Bill Discounting: Convert your unpaid invoices into immediate cash by selling them (bills receivable), improving liquidity without waiting for customer payments.
- Letter of Credit: A bank guarantee to suppliers ensuring payment, useful for establishing trust in new business relationships or large transactions. It helps to purchase goods and pay later.
A Working Capital Loan can help businesses meet recurring and short-term operational requirements. Depending on your business needs, the funds can be used for:
- Inventory and stock purchases: Maintain adequate stock levels, purchase raw materials or prepare inventory for periods of higher customer demand.
- Supplier and vendor payments: Manage outstanding supplier payments and maintain continuity in your procurement cycle.
- Employee salaries and wages: Meet payroll obligations during temporary cash flow shortages or periods where receivables are delayed.
- Rent and utility expenses: Manage recurring operating expenses such as office or store rent, electricity and other essential utilities.
- Seasonal working capital requirements: Access additional funds when inventory and operating expenses increase during peak business periods.
- Equipment repairs and maintenance: Meet essential repair or maintenance expenses required to keep daily operations running.
- Temporary cash flow gaps: Bridge the timing difference between outgoing operational expenses and incoming customer payments.
A wide range of business entities can apply for this loan and benefit from its advantages:
- MSMEs: Micro, Small, and Medium Enterprises registered under the MSME Act can apply for working capital loans to meet their operational expenses.
- Sole Proprietors: Individual business owners operating as sole proprietors are eligible to apply for working capital financing to support their business operations.
- Retail Shop Owners: The retail shop owners, including stores, showrooms, and outlets can access working capital loans for inventory management and stock purchases.
- Women entrepreneurs: Women entrepreneurs who own or lead businesses across various sectors can apply for working capital loans and benefit from special government schemes with preferential terms.
- Small business owners: Small business owners, including traders, distributors, wholesalers, service providers, manufacturers, and even home-based businesses, can apply for working capital loans.
Consider the following tips to increase your chances of a quick and successful loan approval:
- Be Clear About Your Fund Requirement: Have a clear plan for how you intend to use the loan amount to improve your business operations.
- Maintain a Good Credit Score: A healthy credit score (typically 700+) significantly improves approval chances and may fetch better interest rates.
- Keep Your Documents Ready: It is important to have all the required documents organised and ready for submission, which will speed up the verification process.
- Borrow Responsibly: Apply only for the amount you genuinely need. Overborrowing increases EMI burden and can strain cash flow.

Happy Customers, Happy Us
Business Loan
Securing a business loan marked a pivotal moment for our growth. The funds enabled us to invest in new equipment and significantly expand our operations. The team was transparent, supportive, and guided us every step of the way, making the entire process smooth and reassuring
Business Loan
I never imagined getting a loan could be this easy. With minimal documentation and quick disbursement, the process was incredibly smooth. It came at a crucial time and helped me manage my cash flow effectively.
Business Loan
The business loan gave me the confidence to take on larger projects. With competitive interest rates and flexible repayment terms, the experience was smooth and empowering. Truly a great experience.
Business Loan
Excellent service and timely support! The loan enabled me to renovate my setup and enhance the customer experience. I'm truly grateful for the professionalism and efficiency throughout the process.
Business Loan
The loan helped me stock up inventory just in time for the festive season. Approval was swift, and the team truly understood my business needs. A smooth and supportive experience all around!
Business Loan
I was initially hesitant, but the loan process was so well-managed that I felt confident every step of the way. It enabled me to open a second outlet and expand my brand - an experience that truly exceeded expectations.
Business Loan
The loan allowed me to upgrade my machinery and significantly boost production efficiency. The terms were clear, and the service was handled with utmost professionalism.
Business Loan
I’ve taken loans before, but this was by far the most seamless experience. The team was highly responsive, and the funds played a crucial role in digitising my business operations. Truly a smooth and supportive journey.
Business Loan
The business loan came at just the right time, allowing me to stock up on raw materials and stay ahead of seasonal demand. What impressed me most was the repayment structure; it aligned perfectly with my cash flow, making the entire experience stress-free and sustainable.
Business Loan
Taking the loan was a bold move that transformed my business and boosted revenue. It gave me the financial push I needed to take that leap, and I’m glad I did. The support made a real difference in turning plans into progress.
I run a chain of pharmacy stores with 5 branches in Pune. With the growing popularity of home delivery, my customers were expecting the same from me as well. However, the extra capital requirement made it difficult for me to hire delivery persons. With Poonawalla Fincorp’s Business loan, I am now able to compete with online pharmacy retailers, manage working capital and upgrade my system. My customers have grown 50-60%. The loan application process is digital, simple and speedy. I was delighted to get my loan amount disbursed quickly, allowing me to upgrade my operation seamlessly.
Business Loan
The interest rates were fair and competitive, making it easy to manage cash flow for me. The process was smooth with the service and giving a rating of 10.
Business Loan
I was hesitant at first, but the team explained everything clearly and made me feel confident. The loan helped me manage working capital and grow my business steadily.
Business Loan
I was impressed by how quickly my business loan was processed. The team was extremely helpful and guided me through every step. Thanks to their support, I was able to expand my operations without any hasstle.
Business Loan
The loan process was incredibly smooth, and the team was always available to answer my queries. With the funds, I was able to renovate my store and attract more customers. Truly grateful.
Business Loan
Getting a business loan felt daunting at first, but the entire experience was smooth and transparent. The loan helped me purchase new equipment and increase production. Highly recommend their services!
Business Loan
Excellent service and prompt communication. The loan process was seamless, and the funds were disbursed faster than expected. It’s great to work with professionals who understand business needs.
Business Loan
I needed quick funding to stock up for the festive season, and the business loan came just in time. The Credit Manager was proactive and ensured everything was done on priority. Excellent service!
Business Loan
Thanks to the business loan, I was able to open a second outlet. The team was very supportive and explained all terms clearly. I appreciate the personalized attention I received.
Business Loan
I’ve taken loans before, but this was by far the most professional experience. The documentation was minimal, and the disbursement was fast. I’ll definitely recommend them to fellow entrepreneurs.
Business Loan
The loan helped me bridge a critical cash flow gap during the festive season. The team was approachable and ensured everything was handled efficiently. Great experience!
Business Loan
The business loan helped me hire skilled staff and improved my business. The support from the credit team was outstanding. They understood my business and offered the right solution.
Business Loan
I am very happy with the service of the company and will recommend everyone to take loan from Poonawalla Fincorp.
Business Loan
The loan process was quick and transparent. No hidden charges, and the team guided me at every step. Will recommend everyone.
Business Loan
They didn’t just give me a loan—they gave me peace of mind during a tough time, Happy with the service of Poonawalla Fincorp.
Business Loan
No hidden charges, no surprises. The process was clear and smooth from start to finish.
Business Loan
The team guided me at every step and made the entire experience stress-free, will highly recommend to my friends - rating 10!!!
Business Loan
They tailored the loan to fit my business model. Truly customer-focused and satisfying service given by Poonawalla Fincorp, Highly Recommended!!!
Explore Different Types of Business Loans to Suit Your Needs









Get exclusive access to simplified
Personal Finance
Information at
Poonawalla Fincorp’s
FinHub
-
 business loan17 Sep 2026| 6 min
-
 business loan17 Sep 2026| 4 min
Frequently Asked Questions
A working capital loan is a financing option designed to help businesses manage their day-to-day operational expenses and short-term funding requirements. Businesses can use the funds for expenses such as purchasing inventory or raw materials, paying salaries, clearing supplier dues, covering rent and utilities, maintaining equipment, or managing seasonal increases in operating costs. Working capital finance can also help bridge temporary cash flow gaps when a business has expenses to meet while customer payments or receivables are still pending.
A working capital loan can be a useful financing option for eligible small businesses that need additional funds to manage short-term operational expenses or temporary cash flow gaps. For example, a retailer may need working capital to buy additional inventory ahead of peak demand, while a manufacturer may need funds for raw materials, supplier payments, or recurring operating costs. The right borrowing decision depends on the business's actual working capital requirement, repayment capacity and existing financial obligations.
The time required to obtain a working capital loan depends on factors such as application completeness, document submission, verification, eligibility assessment and internal processing requirements. Keeping the necessary KYC, business and financial documents ready can help avoid unnecessary delays during the application process.
Yes. A working capital loan can help eligible businesses manage several short-term financial requirements, including certain advance payments connected with their operations. Depending on the requirement, working capital funding may help a business pay suppliers, procure inventory or raw materials, cover operating expenses, or address temporary mismatches between payments and incoming cash. This can be particularly relevant when a supplier requires payment before delivering goods or when a business needs to build inventory before receiving revenue from sales. However, businesses should use borrowed funds for the permitted end use and in line with applicable loan terms. It is advisable to assess actual needs and repayment capacity before borrowing.
Taking a working capital loan does not by itself determine whether your business's credit profile improves or deteriorates. Repayment behaviour is an important consideration. Making EMI payments according to the agreed repayment schedule can help demonstrate responsible credit management, while delayed or missed repayments may negatively affect the borrower's credit profile. Businesses should therefore consider their existing financial commitments, expected cash flows and repayment capacity before applying for working capital financing.
Working capital loans are primarily intended to finance operational and working capital requirements rather than long-term capital expenditure. However, the actual repayment period depends on the lender, loan structure, eligibility, and other applicable terms. This means businesses should not evaluate a Working Capital Loan solely by whether it is labelled short-term or long-term. Instead, consider the purpose of the funds, the expected cash flow cycle, and whether the repayment schedule is manageable.
By providing the business with funds in advance, a Working Capital Loan allows it to continue operating while awaiting payment from customersA working capital loan can provide additional funds when a timing mismatch exists between a business's expenses and incoming revenue. For example, a business may need to purchase inventory, pay suppliers, cover employee salaries or meet rent and utility expenses before receiving payments from customers. Working capital funding can help cover these operational expenses during the intervening period, allowing business activities to continue without relying entirely on available cash reserves. It can also be useful during seasonal periods when operating costs temporarily increase.